Thinking about home improvements? Speak to Weston Mortgages Online
Russell Green • May 13, 2026

Adapted from an article in our April newsletter


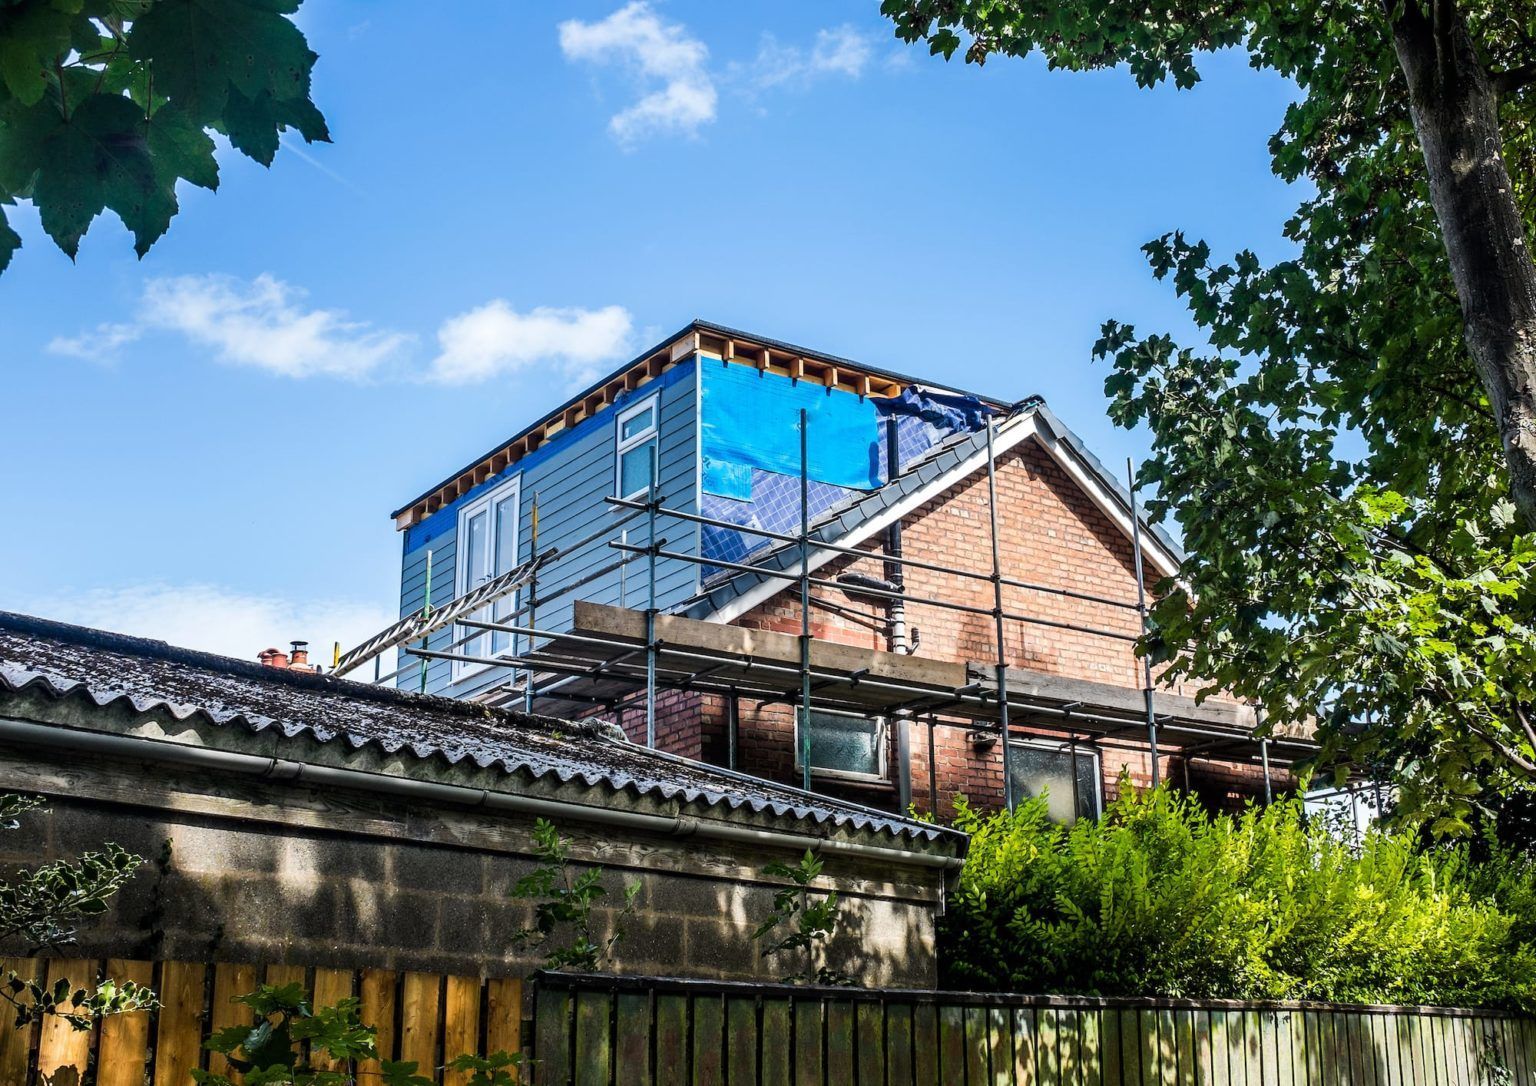
As spring arrives, many people start thinking about making changes to their home. Longer days and better weather can make it a natural time to plan improvements, whether that means building an extension, converting a loft, replacing a kitchen, upgrading a bathroom, improving energy efficiency or making the home more suitable for family life.


Home improvements can add comfort, space and, in some cases, value to your property. However, they can also involve high costs. Materials, labour, planning requirements and unexpected issues can all affect the final amount you need to spend.


If you are considering borrowing more to pay for the work, it is worth speaking to your mortgage adviser before you make any firm commitments. They can help you understand the options available and whether additional borrowing may be suitable for your circumstances.


There may be several ways to fund home improvements. These could include a further advance from your existing lender, remortgaging to raise extra funds, a second charge mortgage, a personal loan or using savings. The right option will depend on your income, existing mortgage, property value, credit commitments, plans and budget.


If you borrow more against your home, your mortgage balance may increase and your home could be at risk if you do not keep up with repayments. This is why it is important to consider whether the borrowing is affordable now and whether it would remain affordable if your circumstances changed.


It is important to look beyond the monthly payment. You should also consider the total cost of borrowing, the interest rate, any fees, the term of the borrowing and whether early repayment charges may apply. Extending borrowing over a longer period may reduce monthly payments, but it could increase the total amount of interest paid.


You should also check whether your current mortgage deal has any restrictions. If you are still within a fixed-rate period, remortgaging before the deal ends could trigger an early repayment charge. In some cases, another borrowing option may be more appropriate.


Before borrowing more, it is sensible to create a realistic budget for the work. This should include the main project costs, professional fees, planning or building control costs where relevant, VAT, temporary accommodation if needed and a contingency for unexpected expenses.


You may also want to consider whether the planned improvements are likely to support your longer-term plans. For example, the work may help you stay in the property for longer, create space for a growing family, improve energy efficiency or make the home more suitable as your circumstances change.


If the work is structural or significant, you should check whether you need planning permission, building regulations approval or consent from your freeholder, landlord or management company. You should also make sure you use suitable professionals and keep records of the work carried out.


Your insurance may also need reviewing. Major building work, extensions or changes to the property could affect your buildings insurance. You may need to tell your insurer before work begins to make sure you remain properly covered.


It is also worth reviewing your wider protection needs. If you increase your borrowing, extend your mortgage term or take on new monthly commitments, you may want to consider whether your life cover, critical illness cover or income protection remains suitable.


Home improvements can be a positive step, but borrowing more should be carefully considered. Taking advice early can help you compare your options, understand the costs and risks, and make an informed decision before you commit.


Please get in touch if you are thinking about home improvements and would like to understand your borrowing options. We can help you compare the possible routes, consider the costs and risks, and decide what may be suitable for your circumstances.


Your home/property may be repossessed if you do not keep up repayments on a mortgage or other debt secured on it.


How to Contact Us

Russell Green will personally deal with your enquiry.

Tel 01934 442023

Email russell@westonmortgagesonline.com

Complete a form via our website www.westonmortgagesonline.com


Our initial mortgage consultation is free and with no obligation; should you proceed to an application, there will usually be a fee for mortgage advice. The precise amount of the fee will depend upon your circumstances, but will range from £ 290 to £490, and this will be discussed and agreed with you at the earliest opportunity.

Your home/property may be repossessed if you do not keep up repayments on a mortgage or other debt secured on it.


All the information in this article is correct as of the publish date 30th April 2026. The opinions expressed in this publication are those of the authors. The information provided in this article, including text, graphics and images does not, and is not intended to, substitute advice; instead, all information, content, and materials available in this article are for general informational purposes only. Information in this article may not constitute the most up-to-date legal or other information.

By Russell Green • November 5, 2026
With mortgage rates climbing and uncertainty surrounding the Autumn Budget, homeowners face a difficult question. Is it better to secure a mortgage deal now or hold out in the hope that rates will fall?
By Russell Green • November 2, 2026
Making extra mortgage payments could help you become mortgage-free sooner. But with savings accounts offering interest too, is paying more towards your home loan always the smartest move? Here’s why speaking to your mortgage broker before making a decision could be worthwhile.
By Russell Green • October 29, 2026
The latest UK Budget announcement, on Wednesday 27 October 2026, brings significant shifts to the property and mortgage landscape. Whether you are trying to buy your very first home, step up the property ladder, or secure a competitive rate for your existing mortgage, the Chancellor’s latest updates will impact your pe
By Russell Green • October 19, 2026
In an era where eco-friendly choices are reshaping how we live, sustainability has officially made its way into the home financing world. If you've been thinking about buying an energy-efficient home or upgrading your current property to make it greener, you might be eligible for a Green Mortgage . Not only do green mortgages help lower your carbon footprint, but they can also offer tangible financial rewards, such as lower interest rates and cashback incentives. Here is a closer look at what green mortgages are, how they benefit you, and why partnering with Weston Mortgages Online is the smartest way to navigate your options. What is a Green Mortgage? A green mortgage is a specialised home loan designed to reward homeowners and buyers for choosing energy-efficient properties or making eco-conscious home improvements. Typically, lenders offer these products to buyers of homes with a high Energy Performance Certificate (EPC) rating (usually band A or B ). Alternatively, some green mortgage products provide preferential terms or additional borrowing options if you commit to energy-efficiency upgrades—such as installing solar panels, double glazing, heat pumps, or improved wall insulation. y Benefits of Going Green with Your Mortgage. Potential Interest Rate Discounts: Many lenders offer discounted interest rates on green mortgage deals compared to standard mortgage products. Lower Energy Bills: Living in an energy-efficient home naturally leads to reduced utility bills, helping you save money month after month. Cashback Incentives: Some mortgage providers offer special cashback rewards upon completion when purchasing an eligible green property. Future-Proofing Your Investment: As energy efficiency regulations evolve and buyer preferences shift toward eco-friendly living, energy-efficient homes often retain stronger market value. Why Choose Weston Mortgages Online? Navigating the mortgage market can feel overwhelming, especially with specialised products like green mortgages entering the mainstream. That’s where Weston Mortgages Online comes in. Access to a Wide Selection of Lenders At Weston Mortgages Online, we search through a wide range of lenders to find green mortgage deals tailored specifically to your financial situation and property requirements. Expert, Tailored Advice Every borrower's situation is unique. Russell Green, ur experienced mortgage broker, simplifies complex terms, checks EPC requirements, and helps you understand whether a green mortgage—or a traditional mortgage—is truly the best fit for your budget. Hassle-Free Management From application approval, we handle the paperwork and liaise with lenders on your behalf, making the entire process smooth, transparent, and stress-free. Claim Your Free Consultation Ready to explore your options without any upfront commitment? Weston Mortgages Online offers a Free Initial Consultation . We’ll review your goals, check your property’s eligibility, and show you how much you could potentially save. Ready to Take the Next Step? Whether you're buying a brand-new eco-friendly home, remortgaging, or planning energy-efficient renovations, let us guide you toward a more sustainable and cost-effective future. What to do next Russell Green will personally deal with your enquiry. Tel 01934 442023 Email russell@westonmortgagesonline.com Our initial mortgage consultation is free and with no obligation; should you proceed to an application, there will usually be a fee for mortgage advice. The precise amount of the fee will depend upon your circumstances, but will range from £ 290 to £490, and this will be discussed and agreed with you at the earliest opportunity. Your home/property may be repossessed if you do not keep up repayments on a mortgage or other debt secured on it. #MortgageAdvice #InterestRates #Remortgage #WestonMortgagesOnline #FinancialPlanning GreenMortgage #Sustainableliving #Eco-mortgage
By Russell Green • October 14, 2026
Getting to that final mortgage approval can sometimes feel like running a marathon. From gathering paperwork and analysing interest rates to trying to figure out which lender suits your unique financial situation, the process can easily get overwhelming.
By Russell Green • October 5, 2026
House hunters are returning after the summer lull, but a bumper choice of properties means buyers can afford to be choosier. Here is what the changing autumn market could mean if you are planning a move.
By Russell Green • September 28, 2026
Struggling to save a huge deposit for your first home? New figures show mortgages for buyers with smaller deposits are accounting for a bigger share of lending. But a 5% deposit does not necessarily mean buying will be affordable, so here is what first-time buyers need to know.
By Russell Green • September 24, 2026
Taking your first steps onto the property ladder is an exciting milestone, but let’s be honest: the world of mortgages can feel overwhelming. Between deciphering interest rates, working out borrowing limits, and keeping track of dynamic market changes, it’s easy to feel stuck before you’ve even booked your first viewin
By Russell Green • September 16, 2026
At Weston Mortgages Online, we believe that getting a mortgage shouldn't involve endless phone calls, complicated paperwork, or days of waiting just to get an initial idea of what you can borrow.
By Russell Green • September 3, 2026
Summer can be a difficult time to read the property market. Families go away, house hunting competes with holidays and good weather, and some of the most reliable housing statistics arrive several weeks after the activity they measure.